

Most people have financial goals. Paying off a credit card, building an emergency fund, buying a first home, or retiring without money stress—the list is familiar because the goals are universal. Yet there is a big difference between wanting these things and actually achieving them. That gap is exactly where budgeting earns its reputation, and it is why so many people ask: how can a budget help you reach your financial goals?
A budget is not a punishment for spending. It is a plan that gives every dollar a job before the month begins—including dollars assigned to your goals. When your goals have their own line items, funded automatically and protected like any other bill, progress stops depending on willpower and starts depending on a system. This guide explains how that system works: what it means to connect goals to a budget, the types of goals worth budgeting for, a step-by-step plan to build one, how to track progress, how to adjust when life changes, the mistakes that derail most budgets, and answers to the most common questions.
What It Means to Connect Goals to a Budget
Connecting a goal to a budget means translating a wish into numbers: an amount and a deadline. “I want an emergency fund” becomes “I will save $6,000 in 12 months, which means $500 per month.” That monthly figure becomes a line item in the budget, sitting alongside rent and groceries—not competing with whatever money happens to be left over.
This shift matters more than any budgeting app or method. Before the connection, every spending decision is judged by “Can I afford this?” After it, the question becomes “Does this move me closer to my goal?” That single change in framing is how a budget helps you reach your financial goals: it turns abstract ambitions into concrete monthly actions.
How Can a Budget Help You Reach Your Financial Goals?

Understanding the mechanics makes it easier to trust the process. A budget supports your goals in six practical ways. First, clarity. Most people underestimate their discretionary spending until they track it. A budget shows exactly where money goes, which reveals the gap between what you earn and what your goals need. Second, prioritization. A budget forces honest trade-offs. Funding a vacation and a debt-payoff plan in the same month may not be possible—and seeing that on paper lets you choose deliberately instead of drifting. Third, automation. The most reliable budgets move money to goals on payday, before it can be spent. Automatic transfers turn “pay yourself first” from a slogan into a default. Fourth, protection against lifestyle creep. When income rises, unplanned spending usually rises with it. A budget assigns raises to goals first, so a bigger paycheck accelerates progress instead of only funding a nicer lifestyle. Fifth, early warnings. Comparing planned spending to actual spending each month catches small leaks—subscriptions, dining out, impulse buys—before they compound into missed goals. Sixth, smaller steps. A $12,000 goal feels impossible; $1,000 a month feels manageable. Budgets shrink big goals into monthly actions you can actually take.
Types of Financial Goals Worth Building Into a Budget
Not every goal belongs in the same budget line, because goals operate on different timelines. Grouping them helps you fund each one at the right pace.
Short-Term Goals (Under a Year)
These are your quick wins: a $1,000 starter emergency fund, paying off one credit card, saving for holiday gifts, or building a car-repair fund. Short-term goals belong in the monthly budget as fixed transfers, and finishing them builds the confidence to tackle bigger targets. Many people find that early wins—like wiping out a small balance—create momentum that carries into harder goals.
Mid-Term Goals (1 to 5 Years)
Mid-term goals need sustained funding: a car down payment, a wedding, a career-change cushion, or growing the emergency fund to three to six months of expenses. Because these take longer, they benefit from their own savings accounts—sometimes called sinking funds—so the money stays separate and visible.
Long-Term Goals (5+ Years and Beyond)
Long-term goals—a home down payment, retirement, a child’s education, becoming fully debt-free—are where a budget quietly does its most important work. These goals are funded by the monthly surplus your budget protects, month after month, year after year. This matches the U.S. Securities and Exchange Commission’s own advice to savers: its roadmap begins by telling people to define their goals and figure out their finances.
A Step-by-Step Plan for Building a Budget Around Your Goals
Follow these steps in order; each one builds on the last.
Step 1: List and rank your goals. Write down every financial goal, then rank them by priority. If everything is a priority, nothing is—pick the top two or three.
Step 2: Make each goal SMART: Specific, Measurable, Achievable, Relevant, Time-bound. “Save for a house” is vague; “Save $30,000 for a down payment in 36 months ($834/month)” is a plan.
Step 3: Do the monthly math. Divide each goal’s total by the number of months until its deadline. This is the monthly funding each goal requires.
Step 4: Track one month of reality. Record all income and all spending for a month. Bank statements and free worksheets make this easier than it used to be—the U.S. government’s financial literacy site offers worksheets and resources for this exact exercise.
Step 5: Fund goals first. Build the budget in this order: goal transfers, essential bills, then discretionary spending. Whatever is left for fun money is genuinely safe to spend.
Step 6: Choose a method that fits your personality. The 50/30/20 rule—50% needs, 30% wants, 20% savings and debt payoff—is a fine starting point. Zero-based budgeting, where every dollar is assigned a job, suits detail lovers. The envelope or cash system suits people who tend to overspend with cards.
Step 7: Automate on payday. Set automatic transfers to savings and investment accounts for the day your paycheck arrives. Automation is the difference between a plan and a result.
How to Track Progress Toward Your Goals
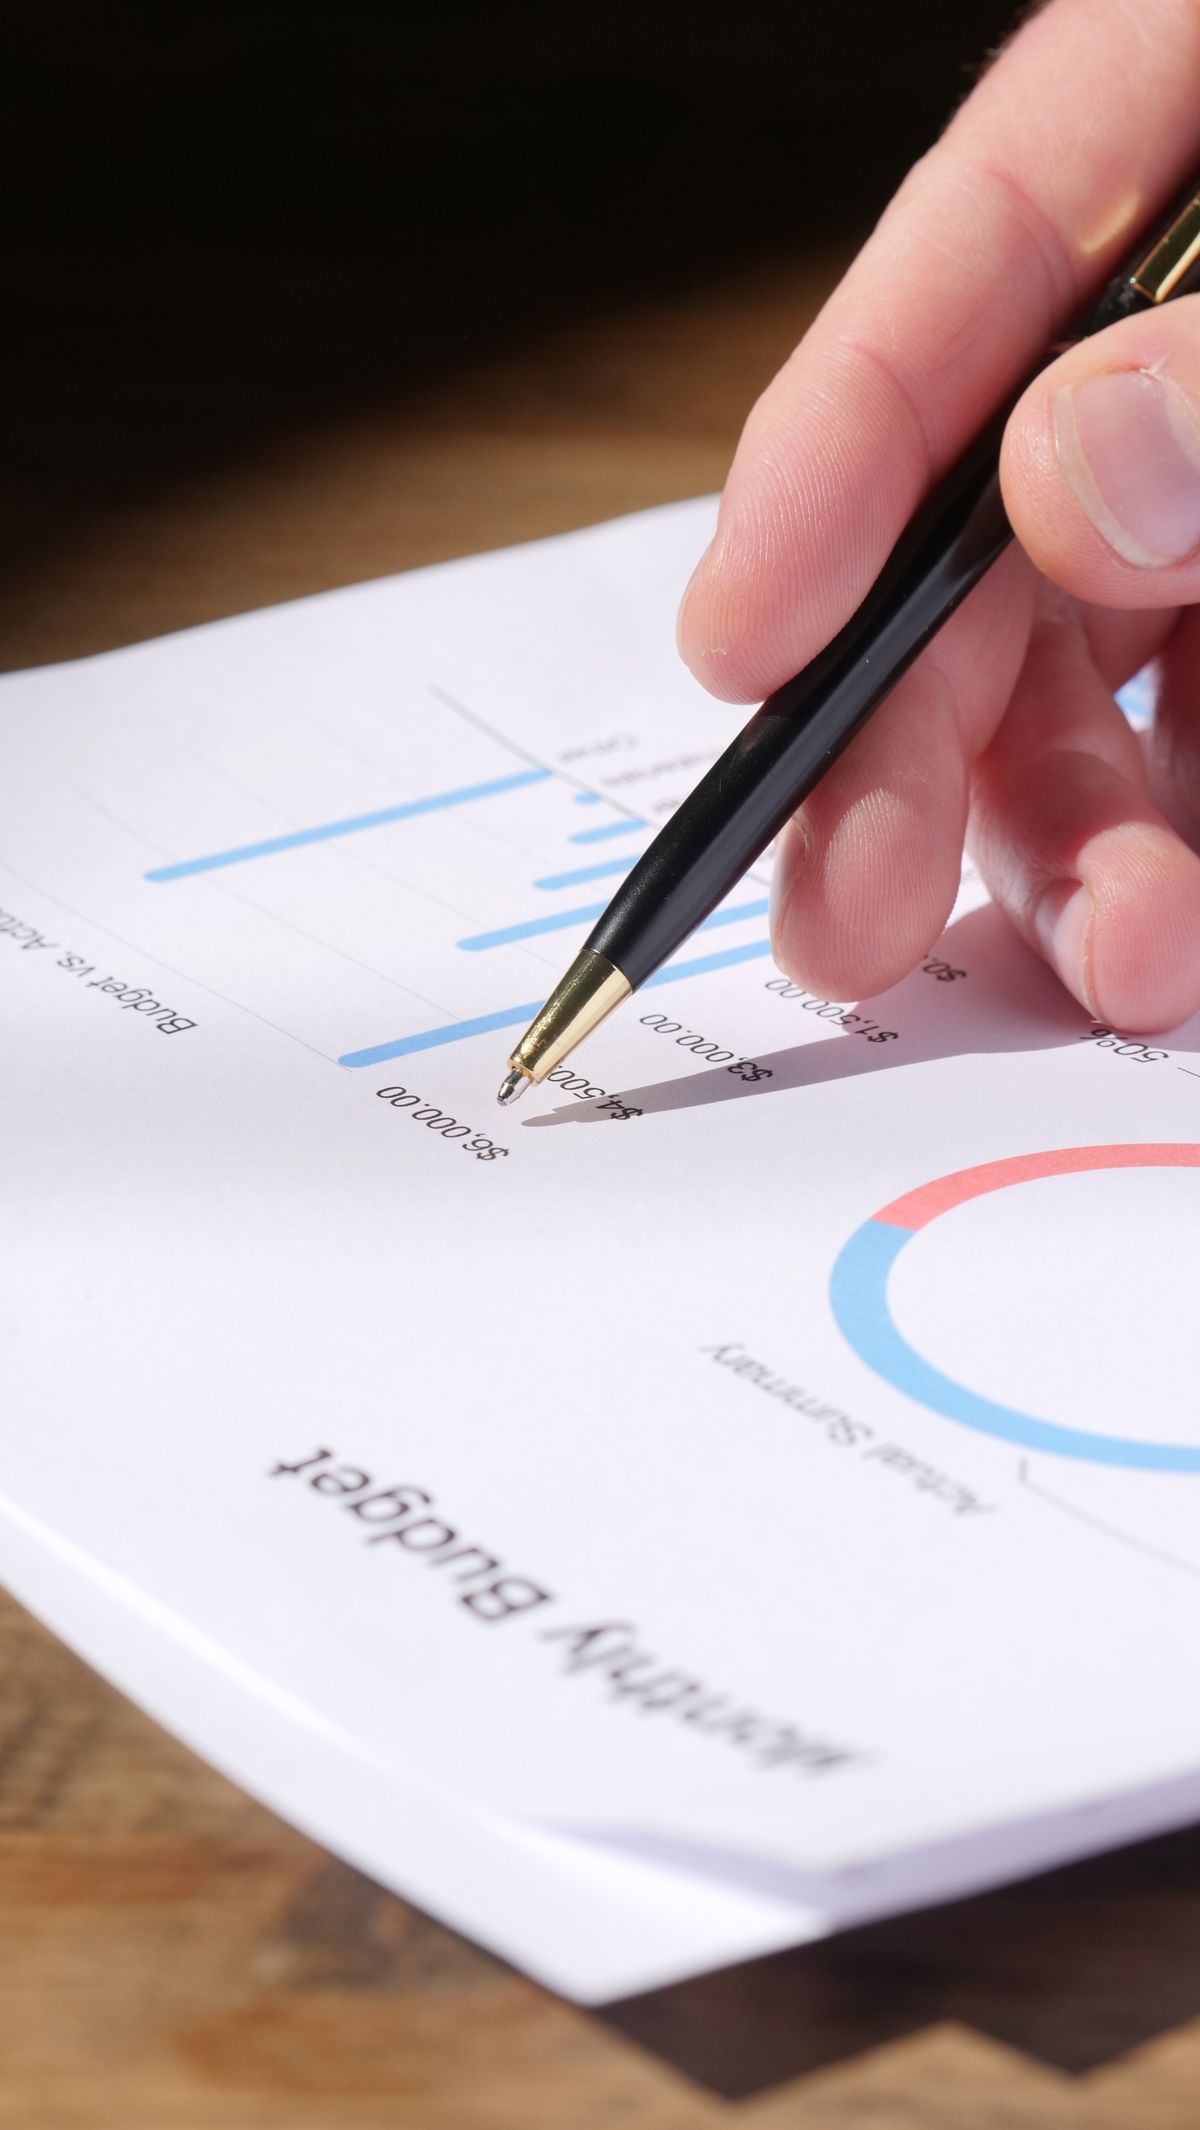
A budget you never review is just a document. A monthly check-in—fifteen minutes with your statements—keeps goals on track. Compare planned versus actual spending in each category and note what drifted. Update a simple progress tracker for each goal: a spreadsheet, an app, or even a hand-drawn chart. Watching a bar fill is surprisingly motivating. Keep mid-term goals in separate sinking funds so progress is visible at a glance. Celebrate milestones cheaply. Hitting 25%, 50%, and 75% of a goal deserves recognition—just not a celebration that raids the goal itself. If a goal falls behind, adjust the timeline or the monthly amount rather than abandoning it. A slower plan you keep beats a perfect plan you quit.
Adjusting Your Budget When Income or Expenses Change
No budget survives first contact with real life unchanged—and that is normal. The strength of a budget is not rigidity; it is that it gives you a clear process for adapting. When income rises, assign at least half of any raise or bonus to goals before your lifestyle absorbs it. Decide the split in advance so the decision is already made. Bringing in extra income—for example, through one of the approaches in this guide to making money online for beginners—only accelerates your goals if the budget directs the extra cash toward them. When income falls, protect the essentials first—housing, food, utilities, transportation—then shrink, but do not necessarily eliminate, goal contributions. An emergency fund exists precisely for this; using it as designed is not failure. When expenses spike, re-run the numbers. Renegotiate bills, pause a subscription or two, and find one spending category to trim temporarily. Small, time-limited cuts are easier to sustain than dramatic overhauls. Revisit the full budget quarterly and after any major life change, such as a new job, a move, or a new family member.
Common Budgeting Mistakes That Sabotage Financial Goals
First, cutting spending to punishing levels. A budget with no room for enjoyment gets abandoned. Leave a realistic amount for fun—sustainability beats severity. Second, forgetting irregular expenses. Annual insurance premiums, holiday gifts, and car registration wreck monthly budgets. Divide each yearly cost by twelve and save for it monthly in a sinking fund. Third, skipping the emergency fund. Without a buffer, every surprise—a car repair, a medical bill—gets paid from goal savings, and progress resets to zero. Fourth, setting it and forgetting it. A budget built in January rarely fits life in July. Review it monthly. Fifth, funding every goal at once. Spreading money across six goals funds none of them meaningfully. Sequence your goals: finish or fully fund the top priority, then move down the list. Sixth, all-or-nothing thinking. One bad month does not ruin a plan. The people who reach their goals are not the ones who never slip; they are the ones who return to the budget the next month.
Frequently Asked Questions About Budgets and Financial Goals
How much of my income should go toward financial goals?
A common starting point is 20% of take-home pay toward savings and debt payoff, as in the 50/30/20 framework. But the honest answer is: start with whatever you can sustain, even 5%. A smaller amount you maintain for years outperforms a heroic amount you abandon in March.
Should I pay off debt or save for goals first?
Do both in sequence: keep a small emergency buffer of around $1,000, then attack high-interest debt aggressively while making minimum payments elsewhere. Once expensive debt is gone, redirect those payments straight into your goals.
What if my income is irregular?
Budget from your lowest typical month, not your average. In good months, fund essentials first, then push the surplus to goals in priority order. Zero-based budgeting—assigning each paycheck as it arrives—works well for freelancers and gig workers.
How often should I review my budget?
A quick monthly check-in plus a deeper quarterly review is enough for most people. Also review after any major change: a raise, a move, or a new recurring bill.
Can a budget really help with long-term goals like retirement?
Yes—indirectly but powerfully. A budget does not invest for you, but it creates and protects the monthly surplus that funds retirement accounts. Consistent contributions over decades matter far more than perfect investment picks, though returns are never guaranteed and it is worth getting professional advice for big decisions.
The Bottom Line: Your Budget Is the Bridge Between Goals and Reality
So how can a budget help you reach your financial goals? By converting wishes into funded plans: naming each goal, pricing it monthly, automating the transfers, tracking progress, and adjusting when life changes. No budget can guarantee results, and no method works without consistency—but a realistic budget, reviewed monthly, is the most reliable system ordinary earners have for turning today’s income into tomorrow’s security. Start with one goal, one monthly transfer, and one check-in. The system does the rest. For more on managing money and building income, browse the Business section of this site, and return to the homepage anytime for the full library of guides.

I’m Nova, a skilled AI content writer with 3 years of experience, specializing in heartfelt prayers, Bible messages, and uplifting spiritual content.